Mortgage criteria myths

Mortgage criteria can be easy to misremember. 

So, before you rule out a case, here are a few Perenna criteria points worth checking. 

Can a client use a loan for their deposit? 

Yes. 

Perenna accepts loans for deposits, subject to affordability and our lending criteria. 

Has a missed payment automatically ruled out the case? 

Not necessarily. In some circumstances, a single missed payment or historic credit issue may still be acceptable. 

Check the current adverse credit criteria for the details. 

Can the product fee be added to the mortgage? 

Yes, in some circumstances. The product fee can be added to the loan where the total LTV does not exceed 95% and the total loan remains affordable. 

Other fees cannot be added to the loan. 

Does existing debt still count if the client plans to repay it? 

No. But, all commitments, regardless of whether they are to be repaid or remain post completion, should be entered into the mortgage application. Debts marked as to be repaid will be excluded from the affordability calculation. 

Can a customer move home with a Perenna mortgage? 

Yes, subject to assessment and valuation. 

Perenna mortgages are portable, so customers can move home and take their mortgage with them, subject to the relevant checks. 

Can’t find the answer in our criteria? 

Ask us. If you have got a complex case or can’t find what you need, contact our Intermediary Support Team. 

It’s better to check than rule out a case based on an assumption. 

Keep checking 

Criteria can change, so check the latest position before submitting. 

View Perenna’s Lending Criteria 

Use our calculator 

Perenna lending criteria applies to new applications only. All applications are subject to affordability checks, credit searches, underwriter assessment and a valuation of the property to be mortgaged. Perenna reserves the right to update and amend its criteria at any time. Meeting the stated criteria does not guarantee that Perenna will lend. 

Correct at time of publishing. 
Making sense of the market: helping clients stay on track

Rates move. Headlines change. Clients notice quickly. 

What they need isn’t urgency, it’s clarity. 

What clients are experiencing 

In changing markets, clients are often: 

  • unsure whether to act or wait  
  • concerned about affordability  
  • worried about rising payments  

This is where clear, practical guidance matters most. 

Moments like this highlight the value of advice. 

Brokers help clients: 

  • understand their options  
  • avoid rushed decisions  

How Perenna supports your cases 

We focus on helping you place cases with confidence. 

Key features: 

  • Fixed rates from 5–15 years  
  • Up to 95% LTV (where criteria allow)  
  • 10% annual overpayments  
  • No ERC on sale or move (subject to criteria)  

Designed to support: 

  • Help to Buy exits  
  • Higher-LTV remortgages  
  • Clients with complex or non-standard profiles  

Why it matters? 

When markets shift, the goal stays the same – to help clients stay in control 

Flexible, longer-term options can: 

  • reduce uncertainty  
  • support planning  
  • avoid unnecessary churn  

Markets will always change. 

Clear criteria, flexible products, and practical support help you keep clients on track – whatever happens next. 

Speak to the team or explore our range. 

For professional intermediaries only.

Correct at time of publishing.

Recap of Perenna Live: Why our 5-year fix is different

The session focused on one key question – How do you give clients certainty without locking them in? 

The webinar addressed common broker challenges, such as: 

  • Positioning medium-term fixes 
  • Simplifying advice conversations 
  • Maintaining flexibility for clients 

Janet and Graham shared live case examples showing how the 5-year fix supports clients who want: 

  • Payment certainty 
  • Flexibility if circumstances change 
  • An alternative to short- or long-term commitments 

During the q&a, brokers also asked practical questions about: 

  • Early repayment charges 
  • Overpayments 
  • Affordability 
  • Foreign national criteria 

Each point was answered clearly, with practical guidance brokers could use straight away. 

Feedback was positive, with attendees praising Graham and Janet for their practical, case-focused approach. 

Missed it? Clips and highlights will be shared on LinkedIn. 

You can also explore Perenna’s full product range or speak to our Business Development & Intermediary Support team about current cases. 

Look out for future Perenna Live sessions coming soon.

Correct at time of publishing. 

We welcome PRIMIS to our growing broker network

Brokers can now offer our full suite of long-term fixed-rate mortgages, including the new 7, 10 and 15-year products. 

Our recently launched 7-15 year fixed-rate range offers: 

  • No ERCs when clients move home or sell the property
  • Flexible overpayments, up to 10% per year
  • Up to 6× income (subject to criteria) at 95% LTV
  • No maximum age limits

These products are offered alongside our already established 40 year fixed rate mortgages, and RIO products.  

This partnership gives brokers more ways to support a wide range of customers with mortgages that are simple, predictable, and built for the future. 

We work closely with a select group of FCA-authorised intermediaries. If your firm is not partnered with us yet, you can register to stay informed about future chances to join the panel. 

Have a question or a case to discuss? Our team is here to help! Call us on 0333 344 1013 or use webchat during office hours. 

Correct at time of publication.

Helping Skilled workers access high-LTV mortgages

Around 150,000 people come to the UK each year on a Skilled Worker visa*. Many of these are Health and Care professionals supporting the NHS. 

For these workers, buying a home in the UK can be challenging. Some high street lenders ask for deposits of up to 25% if applicants do not have Permanent Rights to Reside. 

How Perenna helps? 

We offer lending of up to 95% LTV and 6× LTI for Skilled Worker applicants who meet our criteria. Joint applications are also accepted if the Skilled Worker meets the £50,000 minimum income. 

To qualify, applicants must meet the following criteria: 

  • A minimum annual income of £50,000 for the visa holder. 
  • A minimum residency in the UK of 18 months, with at least 12 months remaining on their visa. 

At Perenna, we are proud to support Skilled Workers with solutions that make homeownership possible, even in a challenging market. 

Our high-LTV lending options give brokers the tools to help clients achieve their goals with confidence and stability. 

Want to see how Perenna can help your clients? Explore our products, check eligibility, or get in touch with our team for guidance on complex cases. 

*Why do people come to the UK? Work – GOV.UK

Correct at time of publication

Affordability with Perenna’s High-LTV lending

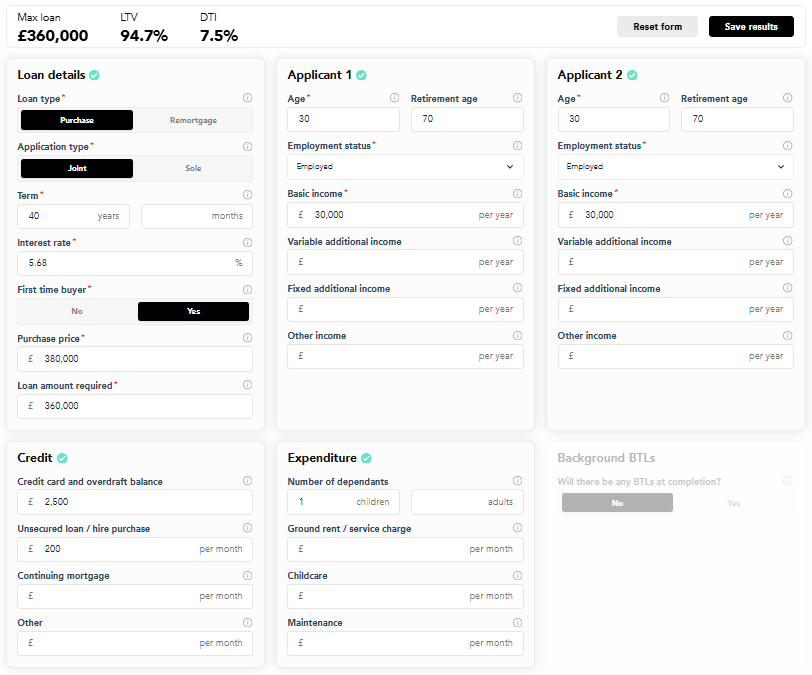
This case study shows how your clients can still get strong affordability with Perenna, even at higher LTVs*. 

Case study overview 

Two applicants, each earning £30k per year, are looking to buy a new home at 95% LTV. 

They have: 

  • One dependent child 
  • A £200 per month loan 
  • £2,500 on a credit card 

Despite these commitments, they are still able to achieve 6x their joint LTI with Perenna*. 

With house prices growing faster than people’s incomes, buying a home is getting harder, particularly for those with smaller deposits or typical salaries. More buyers need solutions that can help close this gap in a safe and sustainable way. 

How Perenna Helps? 

Perenna’s Long Term Fixed Rates and Fixed for Life products are built to give families the stability they need and the flexibility they want. By fixing for the long term, customers get the confidence of predictable monthly payments, without the stress of short-term rate changes or the need to keep switching products. 

Why it matters? 

Helping someone buy a home is not just the mortgage transaction. It is about providing products that support long-term financial wellbeing and make that first step possible. 

With Perenna, more families can access the borrowing they need in a way that is sustainable, transparent, and built for the long term. 

*Subject to criteria.

Calculations correct at time of publication. 

For professional intermediaries only.  

Helping later life clients find the right mortgage

More people are buying their first home in their mid-30s ¹ ². The old idea of retiring in your 50s with a final salary pension is becoming less common. 

As borrowers get older, their financial needs change. Many are now looking for mortgage options later in life, to boost retirement income, support family, or fund lifestyle changes. That is why lenders and advisers need to adapt. 

Understanding the needs of later life clients 

Older borrowers usually have different needs than younger ones. Here are a few important points to consider: 

  • Income: Many rely on pensions, savings, or investments instead of a job. 
  • Affordability: Monthly payments must be easy to manage. 
  • Inheritance: Clients may want to unlock money from their home but still leave something for their family. 
  • Health: Plans should allow for possible care needs and longer lifespans. 
  • Attitude to risk: Old borrowers may be less willing to take interest rate risk and will benefit from longer term fixed rates 

Tailored mortgage solutions 

Perenna offers brokers a range of products to suit older clients: 

  1. Retirement Interest-Only (RIO) Mortgages
  • Clients pay only the interest, so monthly costs stay low. 
  • The loan is paid back when the home is sold, the client moves into care or passes away. 
  • No repayment vehicle is needed. 
  1. Standard Residential Mortgages with Longer Terms
  • Clients can get a full repayment mortgage well into later life. 
  • Interest only mortgages are available where the borrower has a repayment vehicle. 
  • There is no maximum age at application or at the end of the term, and we offer terms up to 40 years. 
  • The mortgage can stay with the home and pass to beneficiaries. 
  1. Downsizing and Moving Home
  • Selling a bigger property and moving to a smaller one can free up money. 
  • It also lowers living costs and helps clients stay financially flexible. 

Key considerations for brokers 

When advising later life clients, keep these points in mind: 

  • Stay compliant: Make sure your advice follows FCA guidelines. 
  • Check affordability: A full income and expenditure check helps find the right solution. 
  • Educate your clients: Clearly explain how each product works, including any risks. 
  • Get families involved: Including heirs in the conversation helps avoid confusion later. 

Final thoughts 

Perenna takes a modern approach to later life lending. Our products offer stability and flexibility, helping older clients make the most of their home’s value. 

Many are equity-rich but cash-poor. With the right support, they can enjoy life now — while they are still healthy and active, and still plan for the future. 

Written by Business Development Manager, Janet Frame. 

Correct at time of publishing.   

Footnote 

¹ Halifax First-Time Buyer Review 2024 – Average age of FTBs is now 33, the highest in two decades.
² TSB via This Is Money, April 2025 – Average first-time buyer now over 30 in all but one UK region. 

Recap of Perenna Live: Perenna summer refresher

New to Perenna or just needed a refresh? Our recent Perenna Live webinar was a reminder of what makes us different and how you can place cases with confidence. 

Our National Account Manager, Deborah Reeves, and our Intermediary Support Manager, Graham Laverty led the session. They walked brokers through the basics such as who we can help, what our lending criteria is, and how to get started with Perenna. 

Who was it for? 

  • Brokers looking for a quick criteria refresher. 
  • Those who have not placed a case with us recently. 
  • Anyone wanting to understand our flexible, fixed-for-term approach. 

What did we cover? 

In this session, we gave a refresher for brokers new to Perenna or those who have not worked with us in a while. 

We covered the core of the Perenna proposition: fixed rates for the entire term, no age limit, and a focus on long-term affordability. We also highlighted the types of clients we support, from high LTV first-time buyers to older borrowers and those with complex incomes. 

We talked about what incomes we accept like pensions, benefits, and money from abroad, and the types of deposits we accept. 

We shared real-life examples, such as gifted deposits, joint applications, and retirement income. During the live Q&A, brokers asked about foreign income, maximum LTVs, and lending to clients with UK travel documents. 

Did you miss it? 

Catch up anytime or connect with your BDM for support: 

  • Speak to your BDM to discuss live cases 
  • Stay tuned for our next Perenna Live session, coming soon… 

We are proud to help brokers place cases with confidence. Brokers trust us because we respond quickly, make things easy, and offer flexible products that work for the long term, especially for clients with unique needs.

Correct at time of publishing.   

Why reaching retirement mortgage-free is no longer the norm

In the past, most people aimed to pay off their mortgage by the time they retired, relying on their pension to cover living costs. If they needed extra money, options like equity release were available. 

But that is no longer the case for many. 

Today, many people retire still owing a large amount on their mortgage. But when they look for support, some high street banks often say no. 

Lenders have not kept up with people living and working for longer. 

Why the change? 

Here is what is driving the shift: 

  • Changing mindset: Easy access to low-interest rates has made debt more common. Many see it as a normal part of life. 
  • Higher living costs: Inflation and rising costs have led to more borrowing for things like cars and holidays. 
  • Regular remortgaging: Many people remortgage to raise capital, adding to their debt instead of reducing it. 

The key point: many people still need mortgage options later in life – and do not know they exist. 

How Perenna can help 

At Perenna, we are making it easier to get a mortgage in later life. Our long-term fixed-rate mortgages offer: 

  • No maximum age at application or at the end of the term 
  • Retirement income affordability, allowing pension income to be used 
  • Flexible repayment options, including repayment, interest-only, or retirement interest-only

For example, Linda and Jack each receive a state pension of around £11,500 a year. Based on their income and no other debts, they could borrow over £100,000 with us at an interest rate of 6.06%.* This could be taken on either a repayment or interest-only basis. 

Stability in uncertain times 

With older borrowers often more vulnerable to interest rate change shocks, our long-term fixed rate mortgages provide the peace of mind and predictability that is crucial later in life. No unexpected rises. No short-term fixes. Just stability – for the full term of the mortgage. 

The bottom line 

Retirement is different today. Whether you are still working or relying on pension income, flexible mortgage options can make a big difference. 

If you have clients in or nearing retirement, contact us today to learn how we can help them maintain financial flexibility. 

Correct at time of publishing.  

Footer 

*Figures correct as of April 2025 and based on typical household expenditure. Actual lending will depend on a full affordability assessment and lending criteria. 

Helping skilled workers achieve homeownership in the UK

In 2024 alone, over 200,000 Skilled Worker Visas ¹ were issued, and many of these went to healthcare professionals like doctors and nurses. As these professionals look to settle in the UK, more are seeking to buy homes here. 

Getting a mortgage as a Skilled Worker or Global Talent Visa holder can be tough. Many lenders require larger deposits or set strict income limits. 

At Perenna, we are proud to offer a tailored solution for these clients. Our lending of up to 95% LTV and 6x income (LTI), subject to criteria offers a flexible and accessible option for Skilled Workers who want to purchase a home and start building their future in the UK. 

Why Perenna’s skilled worker mortgage could be right for your clients

We know your clients do not need more hurdles when buying a home. That is why our mortgage options make homeownership easier for Skilled Workers. Here is what makes our offering stand out: 

  • 95% Loan-to-Value (LTV): This means your clients can get on the property ladder with a smaller deposit. 
  • Up to 6x Loan-to-Income (LTI) subject to criteria: Lending is based on income, making it easier for Skilled Workers to borrow what they need. 

Eligibility criteria 

Here is a simple breakdown of the requirements . 

  • £50,000 minimum annual income for the Skilled Worker Visa holder. 
  • At least 18 months of UK residency, with at least 12 months remaining on the visa at the time of application. 
  • Joint applications accepted: If applying with a spouse, the Skilled Worker must meet the £50,000 minimum income requirement, and the spouse’s income can be added to the affordability assessment. 

Our policy helps Skilled Workers buy their first home with a low deposit, so they can borrow what they need more easily. 

Flexible repayment options

With our long-term fixed-rate mortgages, you can offer your clients the peace of mind that their payments will stay the same.

We also offer a 5-year Early Repayment Charge (ERC) that reduces each year, so if circumstances change, your clients have flexibility. After five years, they can redeem the loan without penalties. 

Let’s talk! 

Do you have clients who are Skilled Workers or Global Talent Visa holders? We would love to help. Perenna’s solutions are flexible, stable, and affordable, making it easier for them to take their next step in homeownership. 

We would love to hear from you! Feel free to reach out to our friendly team to discuss any cases or questions you may have. Contact us today! 

Or why not try out our affordability calculator to see whether Perenna is a perfect match for your clients. 

Written by Perenna’s Intermediary Support Manager, Graham Laverty.

Correct at time of publishing.  

¹ Why do people come to the UK? Work – GOV.UK